
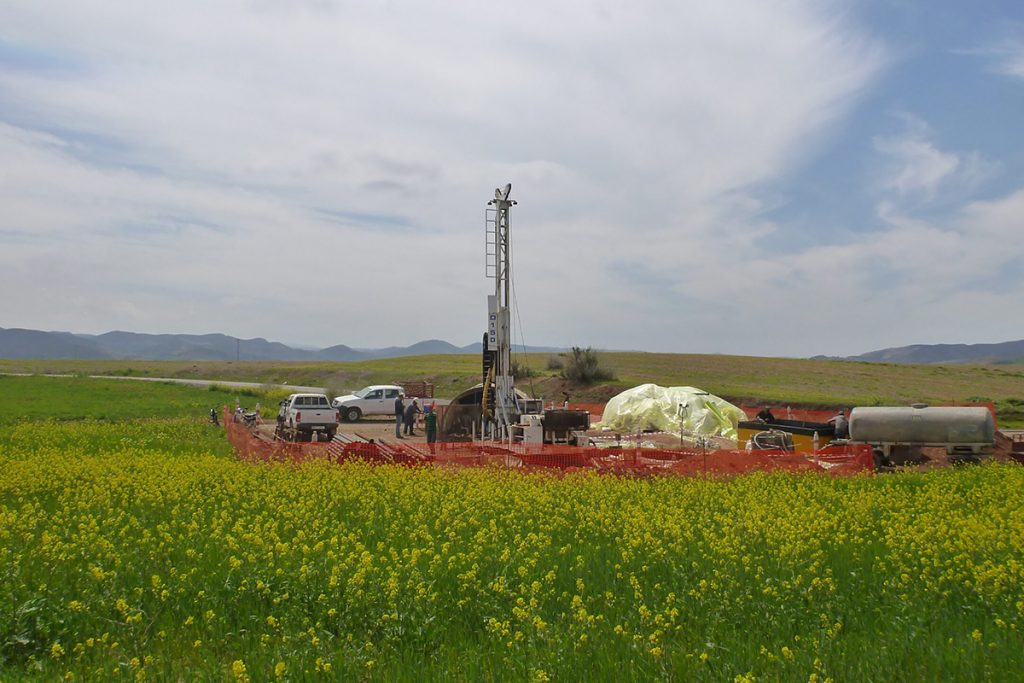
Emmerson plc, the Moroccan focused potash development company, is pleased to provide an important update on the assessment of a conceptual, phased development plan for its 100% owned Khemisset Potash Project (“Khemisset” or “the Project”), aimed at reducing upfront capital costs and incorporating expansion options (RNS dated 17 February 2021).
Highlights
> Conceptual, phased development plan completed resulting in major value enhancing opportunities:
> Significantly reduced up-front capex of US$254.6m (pre-contingency)
> Potential for subsequent phases to be funded from internal cash flows
> Estimated NPV8 US$2.37 billion (assuming phase 4 production)
> Forecast EBITDA in first full year of phase 4 production of US$491.4m
> Demonstration of flexibility and additional potential of Khemisset
> Emmerson to continue Project development utilising outputs of this phased approach study
Overview
Building on the Feasibility Study (‘FS’) (refer announcement 1 June 2020), the Company has completed a concept study to examine the potential to develop Khemisset using a four-phased approach to reduce upfront capital costs and execution risk, and plan additional expansion stages to ensure that its economic value is fully developed.
The intention of the Company remains to build the full-scale project as identified in the FS, however, the report, undertaken to scoping study levels, identifies the opportunity to commence with a smaller scale start-up operation producing Muriate of Potash (“MOP”), which would be followed by a series of expansion phases to increase the level of MOP produced, and add in the production of de-icing salt in increasing quantities as well as premium potash product, Sulphate of Potash (“SOP”).
The upfront capex for this strategy, including contingency, is estimated at US$287m. Subsequent phases through to full production would likely be financed from internal cash flows. In full production, the Khemisset Project could produce 800ktpa of MOP, 240ktpa of SOP and 4mtpa of de-icing salt, resulting in an annual EBITDA in the first year of full production of US$491m. This production rate is a significant increase to the existing FS, which the Company believes is justified given the scale and quality of the Khemisset orebody.
Key metrics of this phased approach are as follows:
Phase 1 | Phase 2 | Phase 3 | Phase 4 | Total | |
MOP Production (t) | 350,000 | 385,000 | – | 270,000 | 1,005,000 |
MOP consumed by SOP production (t) | – | – | (205,000) | – | (205,000) |
MOP Sold (t) | 350,000 | 385,000 | (205,000) | 270,000 | 800,000 |
SOP Production (t) | – | – | 240,000 | – | 240,000 |
De-icing salt (NaCl) Production (t) | – | 1,000,000 | 1,000,000 | 2,000,000 | 4,000,000 |
Capex (incl. contingency) | US$286.9m | US$140.0m | US$143.7m | US$130.4m | US$701.0m |
NPV8 | US$518.5m | US$1.06bn | US$1.71bn | US$2.37bn | US$2.37bn |
Annual EBITDA | US$63.9m | US$199.1m | US$334.1m | US$491.4m | US$491.4m |
Graham Clarke, CEO, commented: “This work demonstrates that the Project has the flexibility to be developed in phases, whilst further proving the world class nature of Khemisset. With significant expansion potential that adds huge value to the Project, we are now confident that we could develop Khemisset using a staged approach potentially reducing upfront capital costs and equity requirements from the market and, therefore, dilution to our existing shareholders as we grow to our full potential.
“2021 continues to be a pivotal year for Emmerson as we move forward in the development of what is to become the first large scale potash mine in Africa.”

 Abmec